We have already helped people in Chelsea...

See what our clients say about us...

Expert Mortgage Advice in Chelsea

Finding the right mortgage starts with knowing which lenders and products may be best suited to your specific circumstances. At Boon Brokers, our expert mortgage brokers in Chelsea provide personalised, whole-of-market mortgage advice across the UK to help you understand your options and make an informed decision.

With access to over 90 UK lenders, we can compare mortgage rates, fees, lending criteria and product features on your behalf. Our expert advice is completely free, with no broker fees to pay, and you will have a dedicated adviser who supports you throughout your mortgage journey.
We're Free. Find Out How...

At Boon Brokers, we don’t believe in mortgage broker fees. So while the average mortgage broker client fee in the U.K is *£600+ – we advise and arrange your mortgage and insurance completely free of charge. Find out how below.

Chelsea Mortgages Made Easy

Searching for the right mortgage in Chelsea can take time, particularly when lenders offer different rates, fees and lending criteria. From comparing your options to completing your mortgage, we’ll handle the details and help make the process as straightforward as possible.

Once you’re ready to proceed, your dedicated adviser will prepare and manage your mortgage application, liaise with the lender and ensure that you’re kept updated throughout.

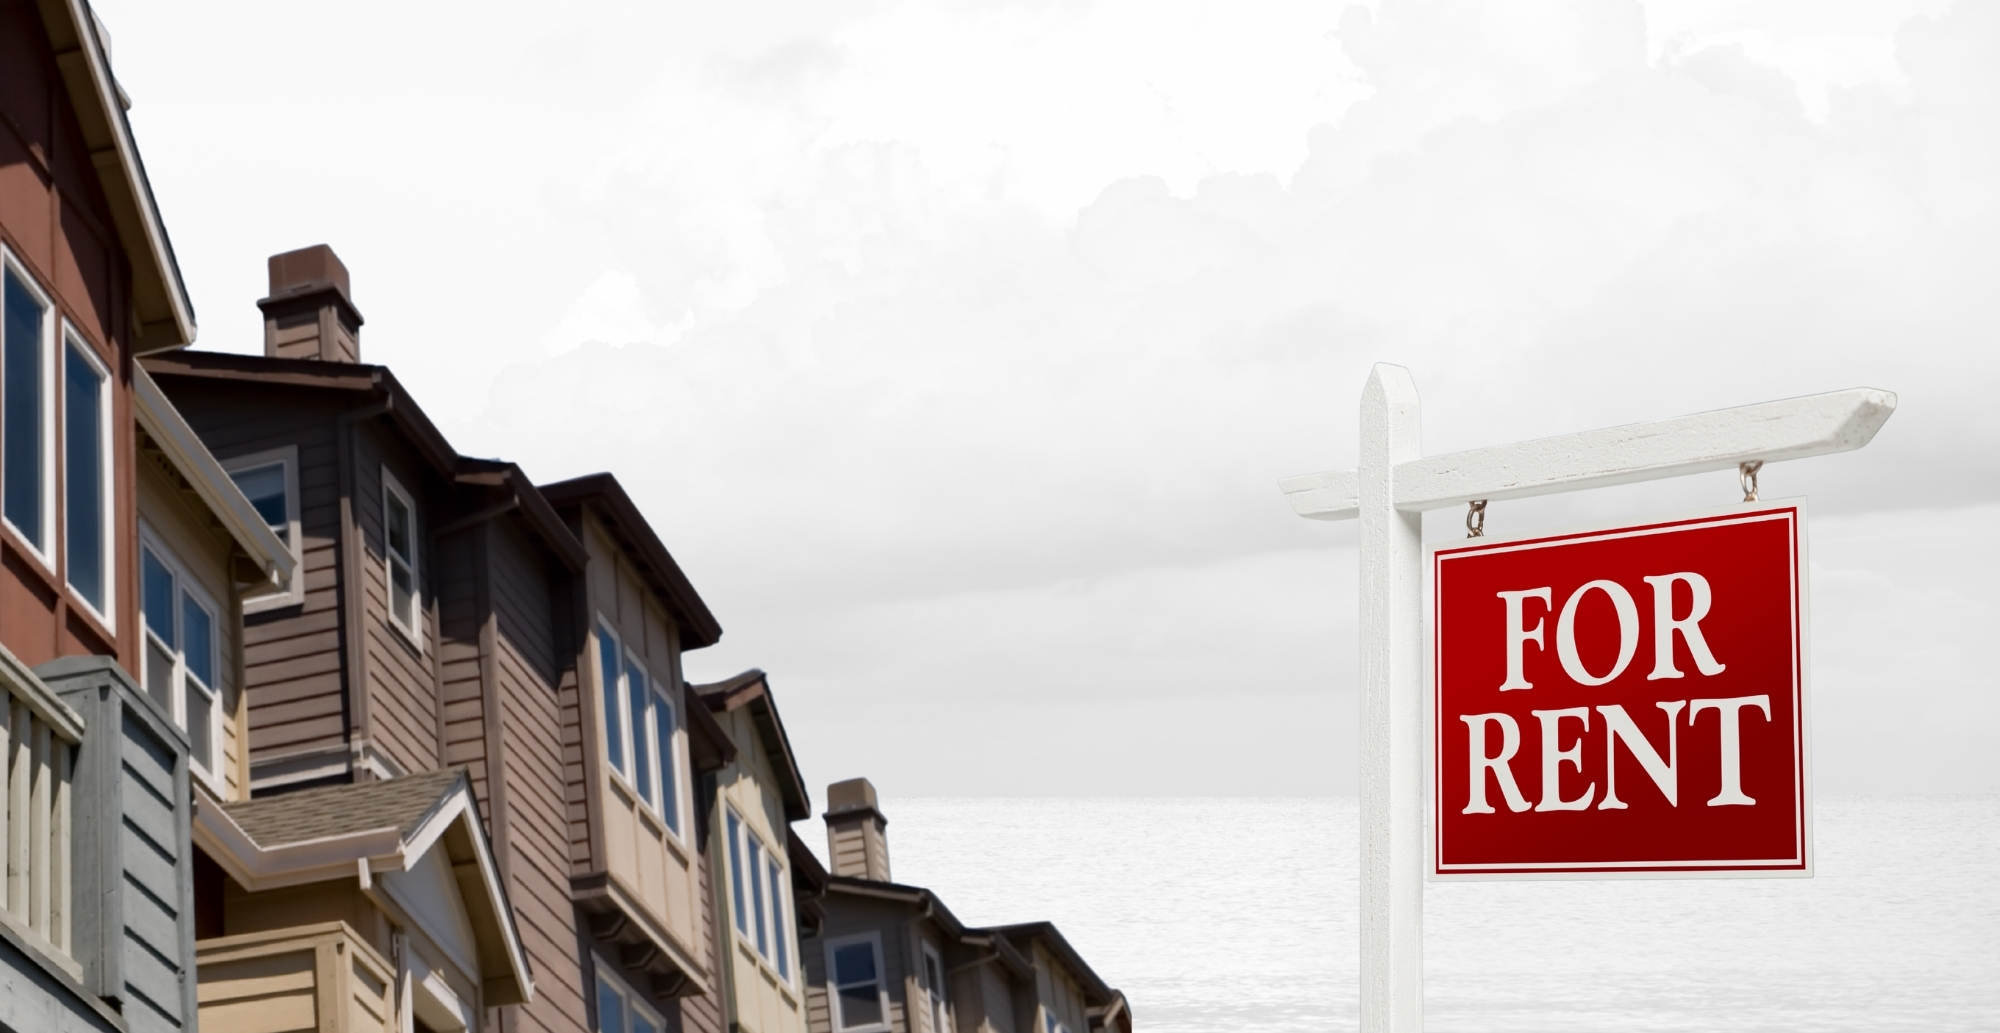
High-angle view of residential rooftops and apartment buildings in Chelsea, London

Living in Chelsea

Chelsea is one of London’s best-known residential areas, combining elegant streets and period architecture with a central location and a strong local identity. The King’s Road runs through the heart of the area, with shops, restaurants and cafés nearby, while Chelsea’s position along the Thames gives parts of the neighbourhood a distinctly riverside character.

Living in Chelsea combines a central London location with a more residential feel than many of the areas surrounding it. Everyday amenities are close at hand, while bus routes and nearby Underground stations make it practical to travel across the capital. Residents also have access to quieter residential streets and green spaces, giving the area some separation from the busier parts of central London.

For buyers looking at properties to buy in Chelsea, where you choose to live can make a noticeable difference. Homes closer to the King’s Road put shops, restaurants and transport within easy reach, while streets towards the Thames can offer a quieter, more residential setting. The local housing stock is equally varied, ranging from converted flats and mansion-block apartments to period terraces and larger family homes.

Average House Price in Chelsea

Official house price data is published for the wider Royal Borough of Kensington and Chelsea rather than Chelsea individually. According to the Office for National Statistics (ONS) data, the average property price across the borough was £1,233,000 in July 2026, making it the most expensive London borough on average that month.

What buyers actually paid varied considerably depending on their circumstances. First-time buyers paid an average of £1,045,000, while home movers paid £1,469,000. For properties purchased with a mortgage, the average was £1,250,000.

These figures provide a useful benchmark for house prices in Chelsea, but the property itself can make a substantial difference to the amount you pay. Across Kensington and Chelsea, flats and maisonettes averaged £972,000, compared with £2,429,000 for terraced properties, highlighting the range of prices buyers can encounter within the local market.

Speak to a Broker

Get Expert Fee-Free Advice to Help You Buy Your Perfect Home in Chelsea.

    Frequently Asked Questions

    Yes. High-value mortgages are available, but lending criteria can become more complex as the amount you borrow increases. Lenders may assess your income, deposit and overall financial position differently, so comparing lenders that are comfortable with larger mortgage loans can be particularly important.
    Yes. Buyers with complex income can still have a wide range of mortgage options. Lenders assess bonuses, commission, dividends and self-employed income differently, so finding one that takes an appropriate view of your earnings can make a significant difference to how much you can borrow.
    Yes. You can get a mortgage for a leasehold apartment, although lenders will usually check the remaining lease length, ground rent, service charges and other lease conditions before approving the property.
    Yes. International buyers may be able to get a UK mortgage, although eligibility can depend on residency, where your income is earned, the currency you are paid in and your UK credit history.
    Yes. You can get a mortgage on period and listed properties, although the property must meet the lender’s requirements. Its age, construction and condition may require additional consideration, particularly if the valuation identifies repairs or features that could affect its suitability for a mortgage.